WLN tag: #taxlaw
Reduced rates of income tax applicable specifically for expats earning income in India orworking in India.
In certain circumstances, expats working in India or earning income in India may enjoy special tax treatment and reduced rates of income tax. 1. Employment income Salary income relating to services rendered in India is deemed to accrue or arise in India irrespective of: Accordingly, such salary income is ordinarily taxable in India. However, expatriate […]
Taxability of Foreign Expats in India: Residential status.
India has emerged as one of the world’s fastest-growing economies and a significant global destination for foreign investment, multinational business operations, technology development, and cross-border employment opportunities. Over the last few decades, the Government of India has progressively liberalised its foreign investment and foreign exchange regulatory framework with the objective of attracting global talent, capital, […]
How are corporations and partnership companies taxed in Italy

If you are planning to establish or acquire a company in Italy, it is essential to analyze the tax regime applicable to corporations and partnerships in Italy. Taxation of corporations In Italy, the main types of corporations include the Limited Liability Company (Società a responsabilità limitata – S.r.l.) and the Joint-Stock Company (Società per Azioni – S.p.A.). Corporations […]
Exit Tax in Poland vs Austria – A Practical Comparison
What is exit tax in principle? “Exit tax” (Wegzugsbesteuerung also called “tax on unrealised gains”) is a set of rules designed to tax latent (unrealised) capital gains when a taxpayer (or assets) leaves a jurisdiction in a way that would otherwise deprive that jurisdiction of its future taxing right on a later disposal. In cross-border […]
Bulgaria: Personal Income Tax
1. General information The Bulgarian personal income tax (PIT) regime is characterized by a notably simple and low-tax structure compared to most European Union jurisdictions. It operates on a flat tax principle, whereby a uniform rate of 10% applies to the majority of personal income categories, including employment income, income from independent activities, rental income, […]
Bulgaria: Residence Permits Overview
I. Long-Term Residence Permit (up to 1 year) – Based on Investment This type of residence permit may be issued to non-EU nationals for a period of up to one year. Permanent residence cannot be acquired under these grounds. 1. Purchase of Real Estate A foreign national may obtain a long-term residence permit for up […]
Poland: Peculiarities of Applying the General Anti-Tax Avoidance Clause
The general anti-tax avoidance clause was introduced into the Polish legal system by the Act of 13 May 2016 and has been in force since 15 July 2016. It is set out in Articles 119a–119f of the Tax Ordinance. The clause allows tax authorities to disregard the tax consequences of actions deemed artificial and aimed […]
WLN Restructuring Focus Group Launch!
We recently announced the launch of the WLN Restructuring Law Focus Group with a brilliant kick-off meeting. As with all our focus groups, the opportunity to meet with fellow lawyers to share experience and legal updates will be invaluable, in addition to building connections with members in different jurisdictions. Sebastiaan Meeuwens (Legalis advocaten) is the […]
WLN Tax Law Focus Group Updates
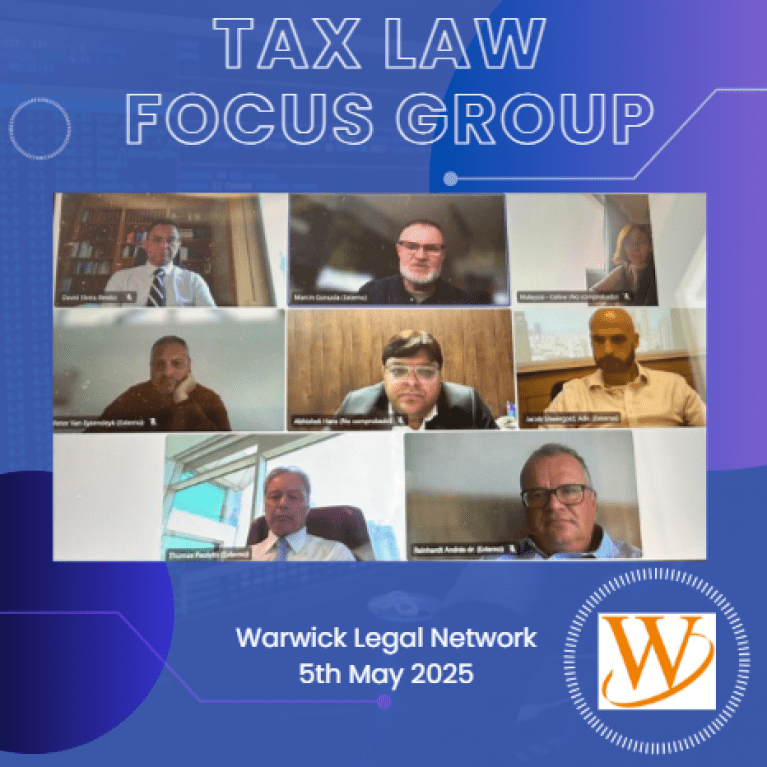
On Monday 5th May, members of the WLN Tax Law Focus Group and ASEAN Legal Alliance met to discuss the current situation with US tariffs and how this can impact us as tax lawyers. Marcin Gorazda led the meeting and was joined by David Elvira Benito, Abhishek Hans, Jacob Shwergold, András Reinhardt, Peter Van Eysendeyk, Thomas Paoletti and Khor […]
Poland: What are the chances of winning a dispute with the tax administration?
When in 1920 a general income tax was introduced in the independent Republic of Poland, after the first few years of its operation, representatives of the legal doctrine and specialists lamented its shortcomings, including, among others, the low quality of the jurisprudence of tax commissions, which resulted in a high rate of repealing decisions issued […]